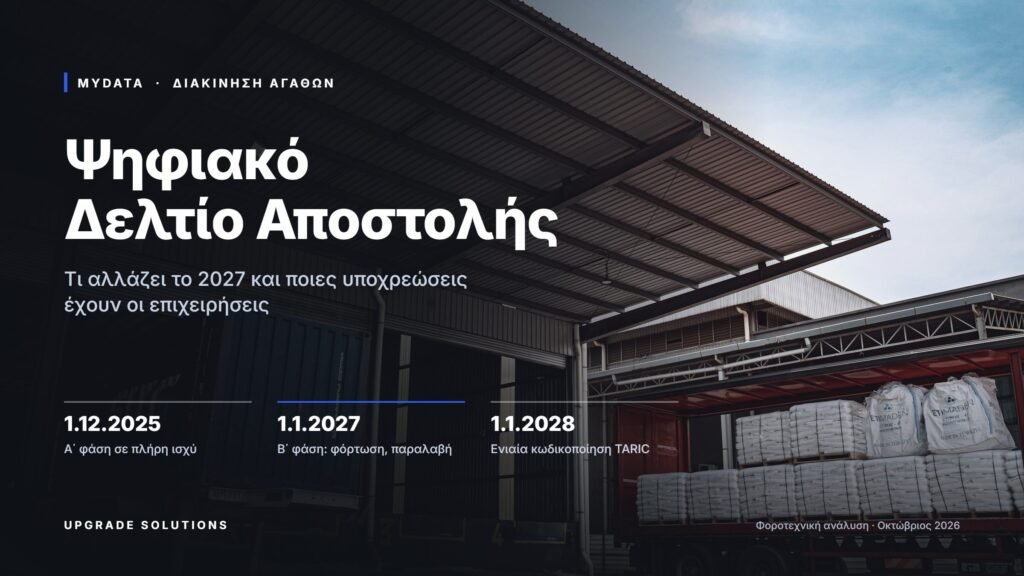
Digital tracking of goods movements is entering its most demanding phase. Phase A of the Digital Delivery Note — the digital issuance of movement documents and their transmission to myDATA — already applies to all obliged businesses. From 1 January 2027, Phase B begins: AADE (the Greek tax authority) will follow every movement from loading to receipt, almost in real time. This changes the daily work of the warehouse, the driver and the accounting department.
EXECUTIVE SUMMARY
- Phase A has been fully in force since 1/12/2025. The old exemptions of POL.1003/2014 ceased to apply on the same date.
- Phase B (loading, transshipment, receipt, quantity check) starts on 1/1/2027 for all businesses.
- Uniform item coding based on the Combined Nomenclature (TARIC) follows from 1/1/2028.
- Moving goods without a digital document: fine of €5,000 or €10,000 per tax audit. Failure to transmit, or late transmission, to myDATA is penalised separately, per violation.
Timeline and legal basis
| Phase | What it covers | Start date |
|---|---|---|
| Phase A | Digital issuance of movement documents and transmission to myDATA. Phased roll-out from 2025. | Fully in force from 1/12/2025 |
| Phase B – part 1 | Digital traceability: loading, transshipment, receipt, quantity-check data. | 1/1/2027 |
| Phase B – part 2 | Uniform item coding under TARIC. | 1/1/2028 |
| Olive growers | Issuance of Phase A documents, provided the olive mill issues a quantity receipt note. | 1/1/2027 |
The framework is based on article 5 par. 9A–9C of Law 4308/2014 (Greek Accounting Standards) and on AADE decisions A.1122/2024 (obliged parties, exemptions, timing) and A.1123/2024 (content, procedure, roles), as amended. The Phase B dates were finally set by the joint decisions of 30 September 2026 (A.1198/2026), after having already been moved from 1/5/2026 to 12/10/2026. Until each obligation starts, transmission of the related data is optional. Implementation guidance is given in circular E.2030/2025.
Who is covered
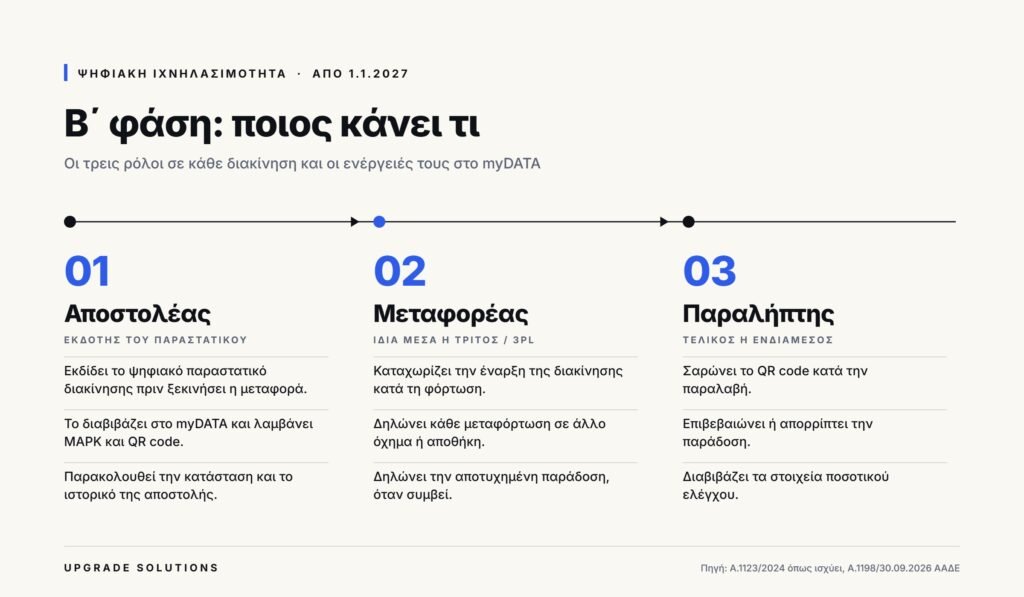
All entities under article 1 of Law 4308/2014 are obliged — sole proprietorships, partnerships and companies — regardless of size or bookkeeping system, whenever they move goods for which a movement document is required. In Phase B every party to the movement plays an active role: the sender, the carrier (own vehicles, a transport company or a 3PL), any third party on whose behalf the shipment is made, and the recipient.
Phase A vs Phase B: the real difference
| Phase A (in force) | Phase B (from 1/1/2027) | |
|---|---|---|
| What is monitored | That a movement document was issued and transmitted | The full journey of the load |
| Who acts | Mainly the issuer | Sender, carrier and recipient |
| Role of the QR code | Verifying the document | Tool for scanning and confirming receipt |
| Receipt | Not recorded digitally | Confirmed or rejected by the recipient |
| Quantity check | No | Transmission of quantity-check data |
Issuance and transmission obligations
- Timing: the document is issued and transmitted before the movement starts. The movement date is the date transport begins, not the arrival date.
- Cancellation: allowed only until the movement starts. After that, corrections follow the prescribed procedures, not cancellation.
- How to issue: through a certified e-invoicing provider, an ERP connected to myDATA, or AADE’s own timologio and myDATAapp applications.
- Loss of connection: a special procedure applies, under strict conditions (see the section “Loss of connection” below). It is not a general alternative way of issuing.
- Voluntary issuance: if you issue a digital document without being obliged to, it must still be transmitted.
Loss of connection: the special procedure and its limits
Circular E.2030/2025 (§12) allows a deviation from real-time issuance only in case of a power outage by the grid operator or a proven inability to connect. A simple delay, a fault in your own software or negligence is not covered.
- Rule: digital issuance. Your system issues the document digitally without interrupting the transaction, with a clear indication that it was issued during loss of connection, and transmits it as soon as the connection is restored (as a general rule, within one day of issuance).
- Exception: handwritten issuance. Allowed only for movements taking place outside the entity’s premises, especially at geographically remote points with limited network coverage. A separate series marked as loss of connection is used, and the data is entered in myDATA through timologio as soon as this is possible. This transmission applies once the related technical implementation is completed (§14).
- Evidence. Keep proof of the outage (notice from the power or internet provider, system logs), because in an audit the burden of proof is on you.
Movements without a sale: when a document is required
The most common mistake we see in practice is skipping the document when there is no sale. The obligation, however, is tied to the movement of goods, not to the sale.
| Case | Movement document required? |
|---|---|
| Transfer between your own premises (intra-company movement) | As a rule, yes. Only movements within the same premises and between registered premises of the same entity up to 10 km apart are exempt. See the conditions below. |
| Shipment to a third-party warehouse (3PL) and from there to a customer | Yes. Who issues depends on the scenario and on who carries the goods. See the scenarios below. |
| Returns of goods | Yes, with a document whose purpose is “return”, linked to the credit note. |
| Fixed assets handed to a third party on loan, lease or free use | Yes, both when sent (issued by the holder) and when returned (issued by the user). |
| Fixed assets sent for maintenance, repair, assembly or disassembly, or for storage at third-party premises | No, provided they are not moved for the purpose of sale |
| Sale of a fixed asset | Yes |
| Sale without physical movement | Not at the time of sale. The document is issued when the goods leave. |
| Purchases from farmers under the special scheme | The buyer issues a quantity receipt note. |
| Imports | If the international transport documents do not show a place of delivery, the importer issues the document. |
Intra-company movements: when the 10 km exemption applies
Decision A.1122/2024 (article 2 case g) exempts only two cases: movement within the same premises and movement between business premises of the same entity located up to 10 km apart. To be covered, all of the following must apply:
- Both the starting point and the destination are premises of the same entity (same tax number). Premises of another company, even within the same group, are not covered.
- Both premises are registered with AADE (head office or branch). A warehouse or space that has not been registered does not count as premises of the entity.
- The distance between them is up to 10 km. In borderline cases, issue a document.
The exemption does not cover movements that start or end outside recognised premises, such as a port, a construction site, a trade fair or a customer’s site. There, a document is issued using the “outside premises” address fields. The same rule applies to moving raw materials to production and finished goods to the warehouse. If you voluntarily issue a document for an exempt movement, it must still be transmitted.
Movements through a 3PL: who issues in each scenario
There is no single rule for every case. Decision A.1123/2024 provides a specific role on the document, the “Third-Party Sender (Commission Agent or Warehouse Keeper)”, and the 3PL may also be the carrier at the same time. Circular E.2030/2025 (§9) offers the following solutions:
| Scenario | Who issues |
|---|---|
| Goods sent by the business to the 3PL warehouse | The business, as owner of the goods, with the 3PL warehouse as the place of delivery. If it has assigned issuance to the 3PL, the 3PL appears in the role of Third-Party Sender. |
| Goods leaving the 3PL for the business’s customer, on its instruction, in two steps (E.2030 §9) | Step 1: the 3PL issues a document to the selling business, with delivery at the warehouse ramp or gate (completion address “outside premises”). Step 2: if the seller carries the goods (own or hired vehicles, or a transport company), the seller issues to the buyer. If the buyer collects with its own vehicles, the buyer issues, with the seller as counterparty. |
| The 3PL itself delivers to the customer as carrier | The circular does not address this explicitly. The roles (issuer, Third-Party Sender, carrier) should be set out in writing in the 3PL contract and supported by your provider. |
The same approach is provided for energy products moving from refineries to airports. Before Phase B starts, agree with your 3PL who issues, who scans the QR code and who confirms receipt in each flow.
Fixed assets: when a document is required
Fixed assets are exempt provided they are not moved for the purpose of sale (A.1122/2024, article 2 case f). According to circular E.2030/2025 (§3–4), the exemption concerns assets the entity uses on a lasting basis in its business:
- Loan, lease or free use by a third party: a document is required. When the asset is sent, the holder issues; when it is returned, the user issues. Example: leased machinery moved to the lessee’s project and back.
- Maintenance, repair, processing, assembly or disassembly: no document required (§4a).
- Storage at third-party premises: no document required (§4b).
- Spare parts moved between your own premises for repair or maintenance and not sold: exempt.
- Sale of a fixed asset: a document is required, as for any goods.
The exemptions
- Movements within the same premises and between registered premises of the same entity up to 10 km apart (under the conditions explained above).
- Retail sales with a receipt. Courier shipments and energy products (e.g. heating oil) are excluded from this exemption and require a document.
- Consumables used in providing services (e.g. cleaning materials), where the fee does not depend on the quantity consumed.
- Fixed assets in lasting use, not moved for sale, that are moved for maintenance, repair, assembly or disassembly, or sent for storage at third-party premises. Loan, lease and free use are not exempt.
- Spare parts between your own premises for repairs, provided they are not sold.
- Damaged or obsolete goods sent for destruction or recycling, provided the four cumulative conditions of E.2030/2025 are met.
- Distribution of free school textbooks, and distribution of newspapers and magazines to news agencies (A.1083/2026).
- Transport of agricultural produce from the place of harvest.
The recipient’s obligations
Phase B shifts significant responsibility to the recipient. In addition to scanning the QR code and confirming or rejecting the delivery, the recipient:
- issues a document or quantity receipt note itself when the sender has no obligation to issue, or has refused or failed to issue,
- for goods from foreign suppliers, transmits a receipt document within five days of receipt,
- as an intermediate warehouse, scans the QR code and does not issue a new document. As final recipient, it issues a new document for every subsequent movement.
Penalties
The Greek Code of Tax Procedure (KFD, Law 5104/2024) provides for two different categories of violation, calculated in different ways. The first concerns moving goods without a document; the second concerns transmitting the data to myDATA.
a) Moving goods without a digital movement document
| Violation | Fine | Legal basis |
|---|---|---|
| Moving goods without issuing a digital movement document (including with a handwritten or non-digital note where a digital one is required) – single-entry books | €5,000 per tax audit | Article 57 par. 13 KFD, as amended by article 214 of Law 5222/2025 |
| The same – double-entry books | €10,000 per tax audit | Article 57 par. 13 KFD |
| Repeat violation | Escalated fine | Article 67 KFD |
The amounts were raised from €500 and €1,000 and apply from the publication of Law 5222/2025 (28/7/2025). The fine is imposed once per audit, regardless of how many movements without a document are found.
b) Failure to transmit, or late transmission, to myDATA
| Violation | Fine | Legal basis |
|---|---|---|
| Movement document not transmitted to myDATA | €100 per violation, capped at €500 per day and €20,000 per tax year | Article 58 par. 3 case d KFD |
| Late transmission | 50% of the non-transmission fine (€50 per violation) | Article 58 par. 5 KFD |
Here the fine is calculated per document, not per audit. Watch the boundary between the two categories: the document must be transmitted before the movement starts. A document that has not been transmitted carries no MARK and QR code from myDATA, so in a roadside check there is a risk it will be treated as a movement without a digital document, with the category (a) fines. The exception is loss of connection under the conditions of E.2030/2025. The way penalties are applied in practice evolves with AADE’s decisions and guidance, so in each specific case check the current regime with your accountant.
Three mistakes to avoid
- Misapplying the 10 km exemption. The exemption covers only movements between registered premises of the same entity. A warehouse not registered with AADE, a construction site or premises of an affiliated company are not covered, however close they are. Check your register of premises now and register any that are missing.
- An e-shop shipping by courier with a receipt only. A retail receipt is not enough when goods are shipped by courier. A movement document is required, with the courier as carrier.
- Cancelling after the truck has left. Once the movement has started, cancellation is not allowed. You need an internal procedure for errors and quantity differences.
Readiness plan for 1/1/2027
| When | Action |
|---|---|
| October | Map all movement flows: sales, intra-company movements, returns, 3PL, imports. |
| November | Talk to your provider or ERP vendor about the Phase B functions: QR scanning, recording loading and receipt. |
| December | Tests with optional transmission, training for warehouse staff and drivers, briefing transport partners and key customers. |
| January 2027 | Full operation and a weekly check of pending receipts in myDATA. |
Frequently asked questions
My small business keeps single-entry books. Does Phase B apply to me?
Yes. The obligation covers all entities under the Greek Accounting Standards that move goods, regardless of the bookkeeping system. The bookkeeping system affects only the amount of the fine.
Do I need to assign TARIC codes now?
Not mandatorily. Uniform coding applies from 1/1/2028, but it is wise to start mapping your items early, especially if you have a large catalogue.
I use AADE’s timologio app. Does it cover Phase B?
AADE has added Phase B functions to timologio and myDATAapp, such as scanning and receiving documents.
The customer does not confirm receipt. Who is responsible?
Confirmation is the recipient’s obligation. As sender, you monitor the shipment status in myDATA and inform the customer. It is a good idea to provide for this in your commercial terms as well.
I move goods to my own warehouse 5 km away. Do I need a document?
No, provided two conditions are both met: the warehouse and the starting point are premises of the same business (same tax number) and both are registered with AADE. If the warehouse has not been registered or belongs to another company, a document is required. If you are unsure about the distance, issue a document.
What if the internet goes down in the truck or the warehouse?
If there is a power outage or a proven inability to connect, your system issues the document digitally with a loss-of-connection indication and transmits it as soon as the connection is back. A handwritten document is allowed only for movements outside your premises, at remote points with limited coverage, in a separate series. Always keep evidence of the outage.
Upgrade Solutions gets you ready for Phase B
We map your company’s movement flows, check your premises in the AADE register, coordinate your provider or ERP and train your team, so that 1/1/2027 does not catch you unprepared. Contact us at info@upgradesolutions.gr.
Read also: E-invoicing in Greece: what changes from 2 November 2026
Sources: Law 4308/2014 (article 5 par. 9A–9C), AADE decisions A.1122/2024, A.1123/2024, A.1083/2026, A.1198/2026, circular E.2030/2025, Law 5104/2024 (KFD, articles 57, 58 and 67), Law 5222/2025 (article 214). Photos: Unsplash.
This article is for information purposes only and does not replace specialised professional advice.